Cross Border Tax Certainty
A single tax dispute can undo years of careful cross border Tax planning. Just ask Cairn Energy, the UK oil major that spent over a decade fighting a retrospective tax demand from the Indian government, a fight that began with a routine internal reorganisation in 2006 and ended with a landmark international arbitration award in 2020. If you are structuring a cross-border investment, planning an overseas expansion, or advising a multinational client on Indian operations, the real lesson is not about oil and gas. It is about cross-border tax certainty, and why it can never be treated as a one-time compliance checkbox.
Why Cross Border Tax Certainty Matters More Than the Tax Calculation
Most businesses approach cross-border transactions the same way: calculate the tax outgo, structure around it, and move forward. But cross border tax certainty is not about knowing today’s tax rate. It is about understanding how today’s structure, documentation, and business rationale will stand up to scrutiny years later, under a rule that may not even exist yet. The Income Tax Department has repeatedly shown that a transaction considered clean at the time of execution can be reopened when the law, or its interpretation, changes.
The Cairn Energy Case: What Actually Happened
Cairn Energy carried out an internal reorganisation of its Indian business in 2006 to prepare for the 2007 listing of Cairn India. At the time, this was a standard pre-IPO restructuring step. Six years later, following the retrospective tax amendment introduced through the Finance Act, 2012, the tax department revisited the 2006 transaction and treated it as giving rise to taxable capital gains. In 2014, it issued a tax demand of roughly Rs 10,247 crore.
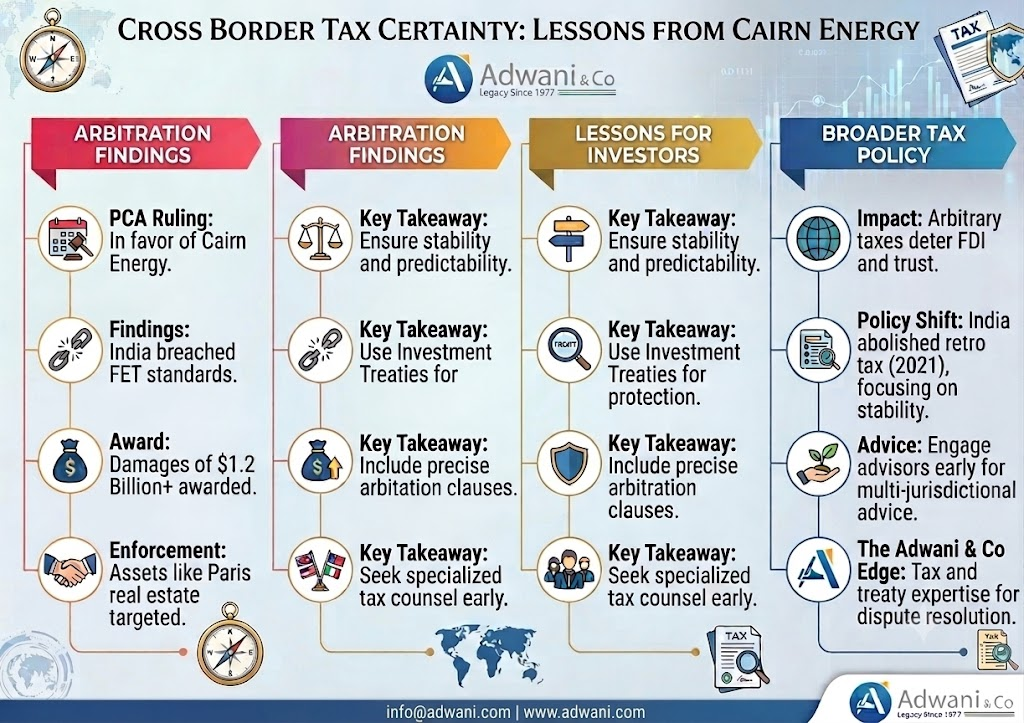
To recover the demand, the department attached Cairn’s residual shareholding in what had by then become Vedanta, seized dividends of around Rs 1,140 crore, and adjusted a separate tax refund of about Rs 1,590 crore against the outstanding claim. Cairn Energy initiated international arbitration in 2015 under the India-UK Bilateral Investment Treaty, arguing that the retrospective demand breached the fair and equitable treatment guaranteed to foreign investors.
In December 2020, the Permanent Court of Arbitration at The Hague ruled in Cairn’s favour, holding that India had failed to honour its treaty obligations, and directed the government to return the funds along with interest and costs. The matter was finally resolved after the Taxation Laws (Amendment) Act, 2021 nullified pre-2012 retrospective demands, prompting Cairn to withdraw its global enforcement proceedings.
What the Cairn Case Teaches About Cross Border Tax Certainty
Treaty Protection Is Not Automatic
Cairn’s arbitration succeeded because it had treaty coverage and could show the tribunal that the demand breached specific investor protections. Not every cross-border structure enjoys this protection by default. Whether a Bilateral Investment Treaty or a Double Taxation Avoidance Agreement applies, and how strongly it applies, depends on how the investment is routed and documented from day one.
Regulatory Change Can Reach Backward
The single most unsettling aspect of the Cairn case is that a 2012 legislative amendment was applied to a 2006 transaction. Cross-border tax certainty planning has to account for the possibility that today’s compliant structure could be judged by tomorrow’s rules, not just today’s.
Documentation Is Your First Line of Defence
Eight years passed between the original transaction and the tax notice. Businesses rarely retain granular documentation, valuation workings, board rationale, and correspondence for that long, yet that is exactly the evidence a tribunal or assessing officer will ask for.
Business Purpose Must Be Provable, Not Assumed
A restructuring done for genuine commercial reasons, such as an IPO, still needs a documented business purpose that can be independently verified years later. Intent alone is not enough; it has to be evidenced.
Exit Plans Need a Tax Lens Too
Cairn’s eventual exit from its Indian holding was disrupted precisely because tax risk had not been priced into the exit structure. Any long-term cross-border decision should be tested against how an exit, sale, or restructuring event might be viewed under future tax scrutiny.
Building Cross Border Tax Certainty Into Deal Structuring: A Practical Example
Consider a mid-sized Indian technology company receiving a $10 million investment from a foreign holding entity, structured through a jurisdiction with DTAA benefits. If the investment agreement, valuation report, and board resolutions clearly document the commercial rationale, and the structure is reviewed against current FEMA and income tax provisions before signing, the business can defend its position even if scrutinised five or ten years later. Without that documentation trail, the same structure could face a reassessment, interest, and penalty exposure running into several times the original tax saved, simply because the “why” behind the structure was never recorded. This is the practical difference cross border tax certainty makes: not lower tax, but a defensible position.
Where Routine Tax Compliance Ends and Cross Border Tax Advisory Begins
Routine tax support answers “what do we owe this year.” Cross border tax certainty requires answering harder questions before the transaction is signed, not after a notice arrives:
- What could change in the regulatory environment over the life of this structure?
- What risks, treaty-related, procedural, or documentary, are we currently missing?
- What happens if the structure itself gets challenged a decade from now?
This is complex advisory work, and it looks very different from annual return filing or routine assessment support. As Dr. Haresh Adwani frequently reminds clients during structuring discussions, the real advisory work happens before the transaction is signed, not after a notice arrives.
How Adwani and Company Helps Businesses Build Cross Border Tax Certainty
Adwani and Company has advised businesses on cross-border and domestic tax positioning since 1977, and this kind of forward-looking risk review is central to how the firm approaches complex advisory mandates. Dr. Haresh Adwani, the firm’s founder, holds a PhD in Commerce and is also a law graduate, a combination that allows him to assess cross-border tax certainty questions from both a tax-technical and a legal-interpretation standpoint. Under Dr. Haresh Adwani’s guidance, the firm’s advisory practice focuses on stress-testing a structure before it is signed, not only reporting on it after the fact.
For businesses exploring cross-border investment, restructuring, or exit planning, this proactive approach is exactly what separates routine compliance from genuine cross-border tax certainty. Learn more about our International Tax Advisory services for a structured review of your cross-border position.
Read our detailed guide on NRI ITR Filing India: Are You Overpaying Tax? for related regulatory considerations.
Government and Regulatory Signals Worth Watching
The Income Tax Department continues to refine its approach to cross-border transactions, and businesses should track its guidance alongside disclosure norms maintained by the
Ministry of Corporate Affairs, particularly where cross-border shareholding, restructuring, or related-party transactions are involved. Staying aligned with these evolving signals, rather than reacting to them after a notice, is itself a form of cross-border tax certainty.
1.What is cross-border tax certainty and why does it matter?
Cross-border tax certainty means structuring a transaction so that its tax treatment remains defensible even years later, under possible future changes in law or interpretation, not just under the rules in force today.
2.What lessons does the Cairn Energy case offer businesses today?
It shows that a transaction considered valid at the time can be reopened years later if the law changes retrospectively, and that treaty protection, documentation, and provable business purpose are what ultimately determine the outcome.
3.Can retrospective taxation still affect current cross-border deals in India?
The Taxation Laws (Amendment) Act, 2021 nullified pre-2012 retrospective demands and limited such taxation to transactions after May 2012, but businesses should still structure deals to survive changes in interpretation, not just changes in law.
4.What documentation protects a business in a cross-border tax dispute?
Board resolutions, valuation reports, correspondence establishing business rationale, and transaction agreements retained well beyond the statutory assessment period are typically what tribunals and tax officers rely on.
5.How does treaty protection work for foreign investors in India?
A Bilateral Investment Treaty or DTAA can protect an investor against unfair or retrospective tax treatment, but the extent of protection depends heavily on how the investment is routed, structured, and documented at the outset.
6.When should a business consult a tax advisor for cross-border structuring?
Ideally before the transaction is signed, when questions about treaty coverage, documentation, and future dispute risk can still shape the structure, rather than after a notice or scrutiny has already begun.
Conclusion: Make Cross-Border Tax Certainty Part of Every Deal
The Cairn Energy dispute is a reminder that cross-border tax certainty is not a formality to tick off during due diligence. It is an ongoing discipline that protects a business’s economics long after the deal is signed. Whether you are planning an inbound investment, an outbound structure, or an exit, the questions worth asking are the same ones complex advisory starts with: what could change, what risks are being missed, and what happens if the structure is challenged.
Author
CA Dipesh Gurubakshani is a Chartered Accountant with Adwani & Co LLP, Pune, specialising in income tax audit, direct taxation, and accounting advisory. He supports clients across statutory compliance, financial reporting, and income tax matters with a focus on accuracy, regulatory adherence, and disciplined execution.
| If you want expert guidance on building genuine cross-border tax certainty into your next transaction, connect with Adwani and Company and Dr. Haresh Adwani’s advisory team today. |
Disclaimer
This article is intended for general informational and educational purposes only and does not constitute legal, tax, or financial advice. The Cairn Energy case details are drawn from publicly reported facts and are summarised for illustrative purposes; readers should not rely on this article as a substitute for professional advice specific to their own facts and circumstances. Adwani and Company recommends consulting a qualified professional before acting on any information contained herein.