Shreya Kavitke I October 2026 | 7 minutes
You donate ₹40,000 to a charity you trust. A volunteer hands you a neat receipt, and you tuck it away, assuming it will do the job at tax time. Months later, while filing your return, you discover that your deduction depends on a different document altogether: Form 10BE.
This guide explains Form 10BE in plain language. You will see how it differs from a donation receipt and Form 10BD, how to claim your Section 80G deduction without trouble, and what has changed now that the Income-tax Act, 2025 is in force.
What Is Form 10BE and Why Does It Matter for Donors?
Form 10BE is the donation certificate that a registered charity or institution issues to a donor after it reports the donation to the Income Tax Department. It is the document that supports your claim for a deduction under Section 80G and, for approved research and similar donations, Section 35.
In the past, a receipt was usually all a donor kept, which left room for mismatches and inflated claims. The law now expects the institution to report eligible donations to the Department and then issue Form 10BE to each donor. In plain terms, the Department can see your donation before you claim it. If your return does not match that report, you may receive a notice or lose the deduction.
Who issues Form 10BE, and who does not?
Only the institution that received your money issues Form 10BE. It first files Form 10BD, its annual statement of donations, by 31 May after the end of the financial year, and then generates the certificate through the Income Tax Department’s e-filing portal. As a donor, you never file either form; you collect the certificate and match it with your return.
Donation Receipt vs Form 10BD vs Form 10BE: The Key Differences
Many donors treat these three documents as one and the same, and that confusion is where claims go wrong.
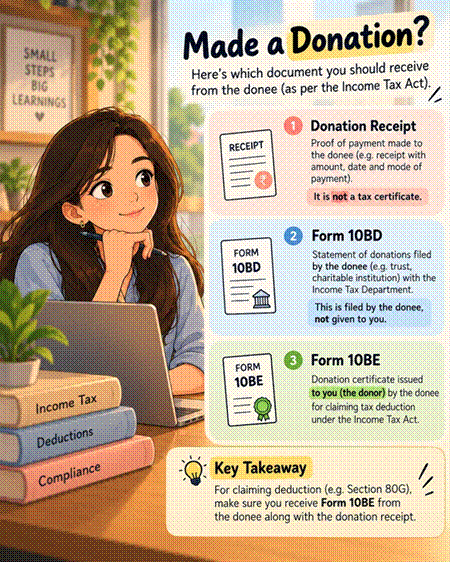
| Document | Prepared by | Given to | Purpose | Tax certificate? |
| Donation receipt | The institution | You (the donor) | Proof of payment: amount, date, mode | No |
| Form 10BD | The institution | Income Tax Department | Annual statement of donations received | No. Not given to you |
| Form 10BE | The institution (after Form 10BD) | You (the donor) | Supports your deduction claim | Yes |
In short, the receipt proves that you paid. Form 10BD is the institution’s annual report to the Department, filed by the donee and never handed to you. Form 10BE is the certificate issued to you to support your deduction, and it is the proof the Department will actually check.
Key Takeaway For claiming a deduction such as Section 80G, make sure you receive Form 10BE from the donee along with the donation receipt.
How to Get Form 10BE and Claim Your Section 80G Deduction
Getting Form 10BE right is mostly about good habits at the time of donating. Follow these steps:
- Check the institution’s approval. Confirm that the institution is approved for donor deductions under Section 80G. Registration as a Section 8 company with the Ministry of Corporate Affairs is not the same as tax approval from the Income Tax Department.
- Pay through a traceable mode. Use cheque, UPI, net banking, or card. A cash donation above ₹2,000 does not qualify for the deduction.
- Give accurate details and collect the receipt. Share your name and PAN exactly as in your tax records, because the institution reports them. Check the receipt before you leave.
- Request Form 10BE after the statement is filed. Ask the institution for Form 10BE once its Form 10BD for the year is on the income tax portal.
- Verify and claim. Check your name, PAN, amount, and section on the certificate, then report the donation in your income tax return along with the certificate details.
Is the Section 80G deduction available in the new tax regime?
Generally, no. The default new tax regime does not allow most Chapter VI-A deductions, and Section 80G is not among the few it keeps. Only taxpayers who choose the old regime can claim a deduction for donations. Check the position for your tax year before planning donations around tax savings.
Form 10BE Under the Income-tax Act, 2025: Form 114 and Section 133
The Income-tax Act, 2025 came into force on 1 April 2026, and it renumbers many provisions and forms. For donations made from that date (Tax Year 2026-27 onwards), the donor deduction that used to sit in Section 80G is found in Section 133, and the reporting forms carry new numbers. The core idea is unchanged: the institution reports, and the donor receives a certificate.
| Item | Income-tax Act, 1961 | Income-tax Act, 2025 |
| Donor deduction | Section 80G | Section 133 |
| Institution’s statement of donations | Form 10BD | Form 113 |
| Donor’s donation certificate | Form 10BE | Form 114 |
Donations made up to 31 March 2026 continue to follow the earlier framework, so the same donor may deal with both sets of numbers while filing returns. We use the familiar name Form 10BE throughout this guide. Always confirm the current form numbers and due dates on the Income Tax Department’s portal before you file.
Transitions are where paperwork slips. Dr. Haresh Adwani, Founder of Adwani and Company, holds a PhD in Commerce and is a law graduate, and that mix of commerce and legal training shapes how our team handles them: we map every donation to the law that applies on its date, then match certificate, receipt, and return line by line. Learn more about our Income Tax Advisory services.
Worked Example: How Form 10BE Changes Your Tax Saving
Example: Anita, a salaried individual who has opted for the old tax regime, donates ₹40,000 by UPI in FY 2025-26 to an approved charity whose donations qualify for a 50% deduction, subject to the qualifying limit. Her adjusted gross total income is ₹12,00,000 (an illustrative figure).
| Step | Working | Amount |
| Donation made by UPI | Traceable mode, so eligible | ₹40,000 |
| Qualifying limit | 10% of adjusted gross total income | ₹1,20,000 |
| Eligible donation | Lower of the two amounts | ₹40,000 |
| Deduction at 50% | 50% of ₹40,000 | ₹20,000 |
| Tax saved | ₹20,000 at 30% plus 4% cess | ₹6,240 |
Now compare the outcomes. If the charity files Form 10BD and issues Form 10BE, Anita claims ₹20,000 and saves ₹6,240. If the charity never reports her donation, the Department has nothing to match her claim against, and the deduction may be disallowed, leaving her with extra tax, interest, and a notice.
Had Anita paid ₹10,000 in cash instead, the deduction would be nil in either case, because cash donations above ₹2,000 are not eligible. These figures are illustrative; check each case against its own facts.
Common Form 10BE Mistakes Donors Should Avoid
- Treating the receipt as the certificate. A receipt proves payment. Form 10BE supports the deduction.
- Donating in cash. Anything above ₹2,000 in cash is not deductible, even if the charity gives you a receipt.
- Giving a wrong PAN or name. A small typo can create a mismatch between the institution’s report and your return.
- Claiming under the new regime. The default new regime generally does not permit this deduction.
- Not following up. If Form 10BE shows wrong details, ask the institution to correct its statement and reissue the certificate before you file.
A short reconciliation before filing prevents most of these. At Adwani and Company, our team reviews donation receipts, Form 10BE certificates, and return entries together, under the guidance of Dr. Haresh Adwani, so that every claim stands on solid paper. Read our detailed guide on Section 80G donation deductions if you want to go deeper.
1.What is Form 10BE in income tax?
Form 10BE is the donation certificate an approved institution issues to a donor after filing Form 10BD. It supports your deduction under Section 80G or Section 35.
2.Is Form 10BE mandatory to claim a Section 80G deduction?
The Department checks claims against the institution’s reported statement, so a claim without Form 10BE is risky and may be disallowed. Collect it before you file.
3.What is the difference between Form 10BD and Form 10BE?
Form 10BD is the institution’s statement to the Income Tax Department. Form 10BE is the certificate issued to you. You never receive Form 10BD.
4.Is a donation receipt enough to claim a tax deduction?
No. A receipt only proves payment and is not a tax certificate. Obtain Form 10BE as well.
5.Is Form 10BE now called Form 114?
For donations under the Income-tax Act, 2025, the certificate is Form 114 and the statement is Form 113. Form 10BE still applies to donations under the earlier law. Confirm on the portal.
6.What if the charity has not given me Form 10BE?
Ask whether it has filed Form 10BD for the year and request the certificate with your payment details. If it does not arrive, consult a tax professional before claiming.
Conclusion: Always Ask for Form 10BE Before You Claim
Giving to a cause you believe in should never turn into a tax headache. A donation receipt shows that you paid, Form 10BD shows that the institution reported, and Form 10BE shows the Department that your claim is genuine. Insist on Form 10BE along with the receipt, match the details before you file, and keep both safe.
About the Author : Shreya Kavitke
Shreya Kavitke is a CA Finalist and an Article Assistant at Adwani & Co. LLP, where she works across diverse areas of taxation, accounting, and regulatory compliance. With a strong academic foundation in commerce and practical exposure to advisory and compliance engagements, she contributes to research and analysis on evolving tax and business regulations.
Her areas of interest include direct taxation, Goods and Services Tax (GST), corporate compliance, and financial reporting.
Shreya contributes articles that combine technical accuracy with practical applicability, helping readers stay informed about key tax developments, compliance obligations, and emerging regulatory trends. She believes that clear, reliable, and timely guidance is essential to navigating today’s dynamic tax environment.
This version reflects the polished, research oriented tone commonly found in publications by leading professional services firms while remaining authentic to Shreya’s current role and experience.